Дипломная (вкр): Исследование эффекта размера на рынках капитала стран БРИКС
Согласно информации, приведенной на рисунках, практически на
всех рассматриваемых рынках наблюдается смещение результатов в отрицательную
полуплоскость, что свидетельствует о наличии отрицательной зависимости между
доходностью акций и их капитализацией. К примеру, на фондовом рынке Бразилии
рост капитализации компании на 1 миллиард бразильских реалов приводит к
снижению доходности акций на 0.001 процентных пункта при прочих равных. Хотя
такой результат экономически невелик, но он статистически значим. Немного
разительная картина наблюдается на фондовом рынке Индии - результаты
статистически и экономически незначимы. Что касается рынка капитала России,
стоит отметить, что в период с 2000 по 2010 и с 2014 по 2016 годы наблюдалась
статистическая незначимость эффекта размера (и соответственно премии за размер
компании), однако в период стагнации с 2011 по 2013 годы аномалия существовала.
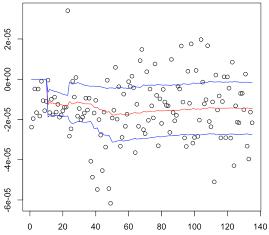
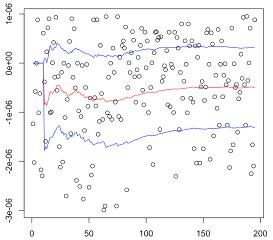
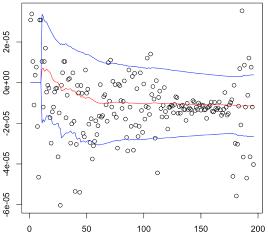
Рис. 6. Динамика значения коэффициента перед регрессором «капитализация компании» в период с 2000 по апрель 2017 год для рынков капитала Бразилии, Индии, России
Источник: составлено автором
Отличительной особенностью рынка капитала ЮАР является
достаточно существенная экономическая значимость эффекта размера компании. Рост
капитализации компании на 1 миллиард южноафриканский рэнд при прочих равных
приводит к падению доходности акции на 0.02 процентных пункта. Результаты
исследования китайского рынка капитала свидетельствуют о том, что эффект
размера не существенен.
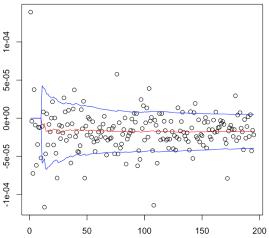
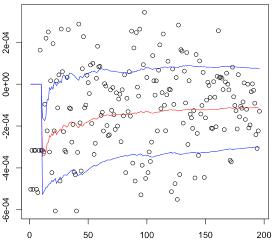
Рис. 7. Динамика значения коэффициента перед
регрессором «капитализация компании» в период с 2000 по апрель 2017 год для
рынков капитала Китая и ЮАР
Источник: составлено автором
Заключение
Широкое распространение исследований, выявляющих, что на доходность капитальных активов могут влиять многие несистематические факторы риска, поставило под сомнение эффективность использования классической модели оценки активов CAPM и работу таких концепций, как гипотеза эффективного рынка и др. Именно по этой причине анализа эффекта размера, как одной из наиболее распространенных рыночных аномалий, приобрело широкий масштаб в академической литературе и финансовых практиках.
Таким образом, исходя из актуальности данной тематики, в данном исследовании была поставлена цель выявить, существует ли эффекта размера на развивающихся рынках капитала БРИКС, и определить величину возможной премии за размер, получаемой инвесторами.
Исходя из глобальной цели в процессе исследование было выполнено следующее:
· определены основные факторы, учитывающиеся при эмпирическом анализа эффекта размера;
· протестирована экономическая и статистическая значимость эффекта размера на рассматриваемых рынках капитала;
· выявлено, каким образом, волатильность и капитализированность рынка капитала, влияет на значимость эффекта размера.
Согласно результатам проведенного исследования, на всех
рассматриваемых рынках капитала, кроме Индии, присутствует эффект размера,
однако, статистическая и экономическая значимость эффекта выше на более
волатильных рынках.
Список литературы
1. Al-Mwalla M., Karasneh M. Fama & French Three Factor Model: Evidence from Emerging Market // European Journal of Economics, Finance and Administrative Sciences. - 2011. - Т.41. - С.132-140.
. Alves P. The Fama French Model or the capital asset pricing model: international evidence // The International Journal of Business and Finance Research. - 2013. - Т.7. - №.2. - С.79-89.
. Amihud Y. Illiquidity and stock returns: cross-section and time-series effects // Journal of financial markets. - 2002. - Т.5. - №.1. - С.31-56.
. Amihud Y., Mendelson H. Asset pricing and the bid-ask spread // Journal of financial Economics. - 1986. - Т.17. - №.2. - С.223-249.
. Banz R. W. The relationship between return and market value of common stocks // Journal of financial economics. - 1981. - Т.9. - №.1. - С.3-18.
. Berk, J. B. (1996), An Empirical Re-Examination of the Relation between Firm Size and Return. Working Paper, University of Washington
. Berk, J. B. (1996), An Empirical Re-Examination of the Relation between Firm Size and Return. Working Paper, University of Washington
. Black, F. (1993), Beta and return, Journal of Portfolio Management, 8 (1993) 18.
. Blume M. E. Betas and their regression tendencies // The Journal of Finance. - 1975. - Т.30. - №.3. - С.785-795.
. Brennan M. J. and Subrahmanyam A. (1996) Market microstructure and asset pricing: On the compensation for illiquidity in stock returns. Journal of Financial Economics, vol.41, no.3, pp.441-464
. Brock W., Lakonishok J., LeBaron B. Simple technical trading rules and the stochastic properties of stock returns // The Journal of finance. - 1992. - Т.47. - №.5. - С.1731-1764.
. Campbell J. Y., Hilscher J., Szilagyi J. In search of distress risk // The Journal of Finance. - 2008. - Т.63. - №.6. - С.2899-2939.
. Carhart M. M. On persistence in mutual fund performance // The Journal of finance. - 1997. - Т.52. - №.1. - С.57-82.
. Chen T. S. and Chien C. C. (2011) Size effect in January and cultural influences in an emerging stock market: The perspective of behavioral finance. Pacific-Basin Finance Journal, vol. 19, no.2, pp. 208-229
. Cho, S. (2012),, The Size Premium: What Role Does Macroeconomic Risk Play? Working paper.
. Chordia T., Subrahmanyam A., Anshuman V. R. Trading activity and expected stock returns // Journal of Financial Economics. - 2001. - Т.59. - №.1. - С.3-32. Чан [Chan et al., 1985]
. Cui, R., Wu, Y. (2007), Disentangling Liquidity and Size Effects in Stock Returns: Evidence from China. Working paper
. Dimson E., Marsh P. Murphy's law and market anomalies // The Journal of Portfolio Management. - 1999. - Т.25. - №.2. - С.53-69. [Dimson et al., 2011]
. Drew M. E., Veeraraghavan M. A closer look at the size and value premium in emerging markets: Evidence from the Kuala Lumpur Stock Exchange // Asian Economic Journal. - 2002. - Т.16. - №.4. - С.337-351.
. Drew M. E. (2003) Beta, Firm Size, Book-to-Market Equity and Stock Returns: Further
. Duff and Phelps, LLC (2012), Duff & Phelps Risk Premium Report 2012
. Evidence from Emerging Markets. Journal of the Asian Pacific Economy, vol.8, no.3, pp.354-379.
. Fama E. F., French K. R.common risk factors in the returns on stocks and bonds // Journal of financial economics. - 1993. - Т.33. - №.1. - С.3-56.
. Fama E. F., French K. R. Dissecting anomalies with a five-factor model // Review of Financial Studies. - 2016. - Т.29. - №.1. - С.69-103. Мартинса [Martinsa, 2014]
. Fama E. F., French K. R. Size, value, and momentum in international stock returns // Journal of financial economics. - 2012. - Т.105. - №.3. - С.457-472.
. Fama E. F., French K. R. The cross‐section of expected stock returns // the Journal of Finance. - 1992. - Т.47. - №.2. - С.427-465.
. Fama E. F., French K. R. Value versus growth: The international evidence // The journal of finance. - 1998. - Т.53. - №.6. - С. 1975-1999.
. Ferdian I. R., Omar M. A., Dewi M. K. Firm Size, Book to Market Equity, and Security Returns: Evidence from the Indonesian Shariah Stocks // Journal of Islamic Economics, Banking and Finance. - 2011. - Т.7. - №.1.
. Gandhi P., Lustig H. Size anomalies in US bank stock returns // The Journal of Finance. - 2015. - Т.70. - №.2. - С.733-768.
31. Garza-Gómez X., Hodoshima J., Kunimura M. Does size really matter in Japan? // Financial Analysts Journal. - 1998. - С.22-34.
. Gaunt C. et al. The illusory Australian small firm premium // JASSA. - 2015. - №.2. - С. 19.
. Grabowski, R., King, D. (2001), The Size Effect and Equity Returns, Appendix 5A in Fishman et al., Guide to Business Valuations, Practitioners Publishing Company.
. Hassan, A., and Javed, M. T. (2011), Size and value premium in Pakistani equity market, African Journal of Business Management, 5 (16) (2011) 674-675.
. Horowitz, J. L., Loughran, T., Savin, N. E. (2000a), The disappearing size effect, Research in Economics, 54 (1) (2000) 83-100.29.
. Horowitz, J. L., Loughran, T., Savin, N. E. (2000b), Three analyses of the firm size premium, Journal of Empirical Finance, 7 (2) (2000) 143-153.
. Hou K., Moskowitz T. J. Market frictions, price delay, and the cross-section of expected returns // Review of Financial Studies. - 2005. - Т.18. - №.3. - С.981-1020.
. Hwang Y. S. et al. Using the credit spread as an option-risk factor: Size and value effects in CAPM // Journal of Banking & Finance. - 2010. - Т.34. - №.12. - С.2995-3009.
. Jianlong W., Jaaman S. H., Samsudin H. B. Empirical study on China stock market base on Fama-French model // Indian Journal of Science and Technology. - 2015. - Т.8. - №.11.
. Keim D. B. Size-related anomalies and stock return seasonality: Further empirical evidence // Journal of financial economics. - 1983. - Т.12. - №.1. - С.13-32.
. Knez, P. J., Ready, M. J. (1997), On the robustness of size and book-to-market in crosssectional regressions, Journal of Finance, 52 (1997) 1355-1382.
. Lakonishok J. and Shapiro A. C. (1986) Systematic risk, total risk and size as determinants of stock market returns. Journal of Banking and Finance, vol.10, no.1, pp.115-132
. Lamoureux C. G., Sanger G. C. Firm Size and Turn‐of‐the‐Year Effects in the OTC/NASDAQ Market // The Journal of Finance. - 1989. - Т.44. - №.5. - С.1219-1245.
. Levy R. A., Repkin A. H., Anderson E. G. The effect of bicuculline on primary afferent terminal excitability // Brain research. - 1971. - Т.32. - №.1. - С.261-265.
. Lu C. C. et al. Bankruptcy and the size effect. - University of Stavanger, 2010. - №. 2010/6.
. Ma, T., Shaw, T. Y., 1990. The relationships between market value, P/E ratio, and trading volume and the stock return of Taiwan Stock Exchange. In: Rhee, S. G., Chang, R. P. (Eds.), Pacific-Basin Capital Markets Research, vol.I. Elsevier, pp.313-335.
. Mirza N., Shahid S. Size and value premium in Karachi stock exchange. - 2008.
. Perez‐Quiros G., Timmermann A. Firm size and cyclical variations in stock returns // The Journal of Finance. - 2000. - Т.55. - №.3. - С.1229-1262.
. Roll R. A critique of the asset pricing theory's tests Part I: On past and potential testability of the theory // Journal of financial economics. - 1977. - Т.4. - №.2. - С.129-176.
. Roll R. A possible explanation of the small firm effect // The Journal of Finance. - 1981. - Т.36. - №.4. - С.879-888.
. Roll R. The behavior of interest rates: An application of the efficient market model to US treasury bills. - Basic Books (AZ), 1970. - Т.1.
. Scholes M., Williams J. Estimating betas from nonsynchronous data // Journal of financial economics. - 1977. - Т.5. - №.3. - С.309-327.
. Sehgal S., Subramaniam S., Deisting F. Tests of equity market anomalies for select emerging markets. - 2014. [Lischewski and Voronkova, 2012]
. Sehgal S., Tripathi V. Size effect in Indian stock market: Some empirical evidence // Vision. - 2005. - Т.9. - №.4. - С.27-42.
. Sehgal S., Tripathi V. Size effect in Indian stock market: Some empirical evidence // Vision. - 2005. - Т.9. - №.4. - С.27-42.
. Starks, L. T., Yong, Li, Zheng, Lu, (2006), Tax-Loss Selling and the January Effect: Evidence from Municipal Bond Closed-End Funds. AFA 2005 Philadelphia Meetings
. Stoll H. R., Whaley R. E. Transaction costs and the small firm effect // Journal of Financial Economics. - 1983. - Т.12. - №.1. - С.57-79.
. Van Dijk M. A. Is size dead? A review of the size effect in equity returns // Journal of Banking & Finance. - 2011. - Т.35. - №.12. - С.3263-3274.
. Vassalou M., Xing Y. Default risk in equity returns // The Journal of Finance. - 2004. - Т.59. - №.2. - С.831-868.
. Xie S., Qu Q. The three-factor model and size and value premiums in china’s stock market // Emerging Markets Finance and Trade. - 2016. - Т.52. - №.5. - С.1092-1105.
. Zhao Z. The Empirical Study of Size Effect, Book-to-Market Effect in US Security Market. - 2014.
. Молодова Е.А., Пирогов Н.К. Затраты на собственный капитал: тестирование трехфазной модели Фамы и Френча на российском рынке капитала // В кн.: Корпоративные финансовые решения. Эмпирический анализ российских компаний (корпоративные финансовые решения на развивающихся рынках капитала) / Науч. ред. : И.В. Ивашковская. М.: ИНФРА-М. - 2011. - Гл.4. - С.48-79.
. Теплова Т.В., Микова Е.С., Шершнева А.А. Особенности построения премий за риск в трехфакторной модели Фама-Френча. Кейс Индонезии // Финансовый менеджмент. - 2017. - №.2. - С.80-94.
. Фомкина С.А. «Эффект размера» и затраты на собственный капитал // Корпоративные финансы. - 2016. - №.3 (39).
Приложения